
What to Know about FHA Appraisals and Property Conditions
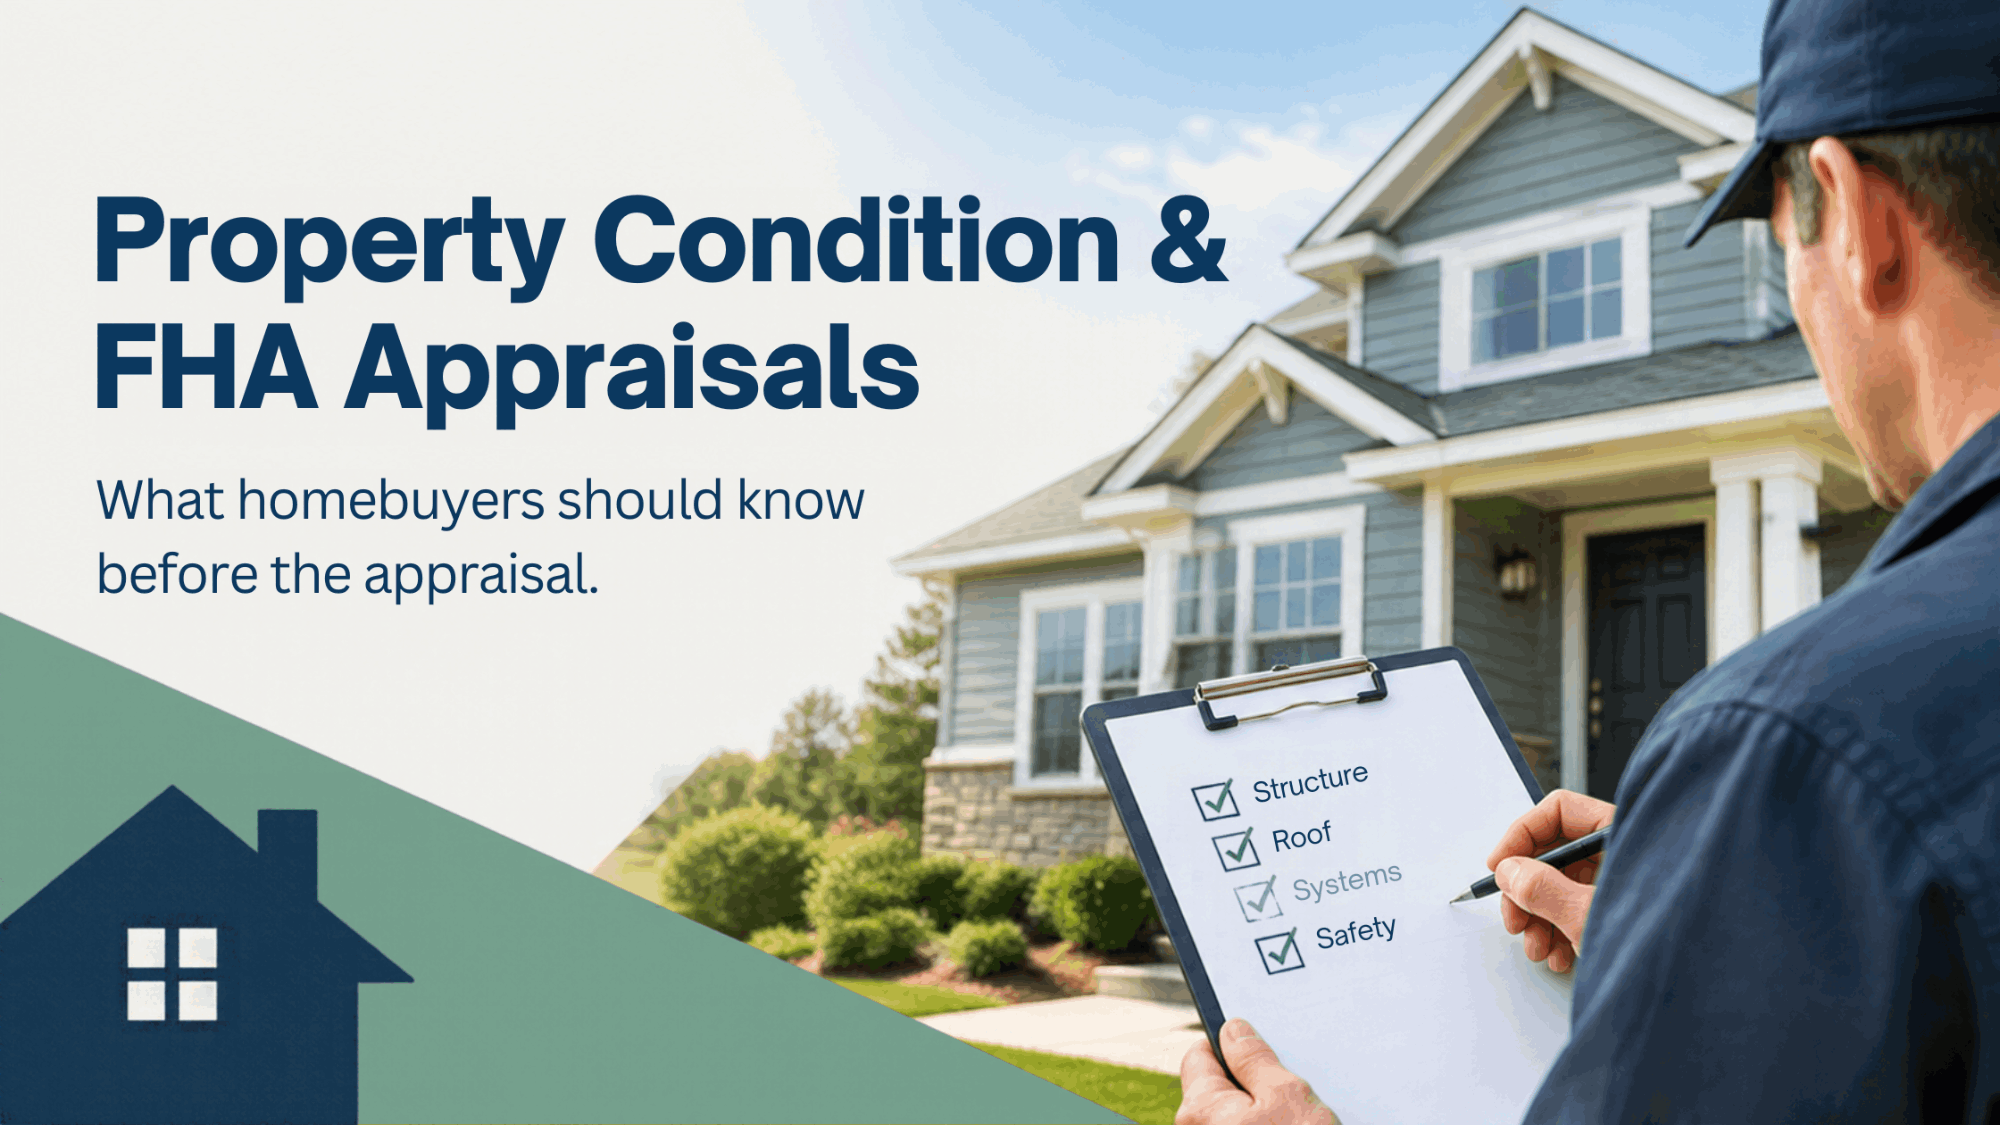
What You Should Know About FHA Appraisals and Property Conditions
A home can look ready to sell and still run into trouble when the buyer is using FHA financing.
After more than 30 years working in the Phoenix real estate market, I’ve seen how a perfectly good deal can get derailed when property condition issues surface late. Issues involving safety, security, or structural soundness may require repairs or further review before the loan can move forward. For agents, finding out late can mean unexpected costs, delays, and difficult conversations with clients.
WHY FHA APPRAISALS ARE DIFFERENT
An FHA appraisal does two jobs. The appraiser gives an opinion of market value, and also reviews certain property conditions. Where a conventional appraisal focuses mainly on value, the FHA appraisal also asks whether the home meets minimum standards for safety, security, and soundness of structure.
That means a home that looks great at a showing can still be flagged for things a typical buyer might never notice.
COMMON CONDITIONS THAT CAN RAISE A FLAG
Every property is different, and the appraiser’s findings will depend on the home. In general, these are the kinds of items that can draw attention:
- Roof condition, especially signs of leaks or a roof near the end of its useful life
- Peeling, chipping, or flaking paint, particularly on older homes
- Missing or damaged handrails, broken stairs, or other trip hazards
- Exposed or faulty electrical wiring
- Plumbing leaks or evidence of water intrusion
- Non-working heating or cooling, or utilities that are not on for the inspection
- Broken or missing windows, or doors that don’t secure properly
- Signs of structural problems, such as foundation cracking or settlement
- Pools, spas, or other features with safety concerns, such as damaged or missing barriers
This is not a complete list, and nothing here replaces the actual FHA guidelines or a qualified inspector’s opinion. It’s meant to show the types of concerns that can slow a file down.
HOW AGENTS CAN GET AHEAD OF IT
- Talk to sellers early. If your listing might attract FHA buyers, walk the property with a critical eye before it hits the market. Small fixes made up front are usually easier and cheaper than repairs negotiated mid-contract.
- Set expectations with buyers. Let FHA buyers know the appraisal includes a property condition review, so they aren’t surprised if repairs are requested.
- Make sure utilities are on. An appraiser who can’t test the systems can’t complete the review, and that can cause avoidable delays.
- Work with your lender. Your loan officer can explain how current requirements apply to a specific property and what happens if repairs are required.
- Build in time. If issues are identified, repairs and re-inspection take time. Plan the timeline accordingly.
A NOTE ON CHANGING GUIDELINES
FHA guidelines can change over time, so always confirm the current requirements with your lender or the official HUD resources. What stays constant is the purpose: identifying important property issues before the loan moves forward.
THE BOTTOM LINE
Preparation protects your clients and your deal. When agents understand what an FHA appraisal looks for, they can have the right conversations at the right time, before a problem becomes a deal-breaker.
If you’re thinking about buying or selling in the Phoenix area and have questions about FHA financing, I’d be happy to help.
David Thomas
Realtor, HomeSmart Realty
Recent Posts
Making real estate fun, simple and stress-free!